How Long Does CIBIL Keep Defaulter Records? Retention Rules Explained (2026)
Missing a credit card payment temporarily drops your score, but a full default leaves a lasting scar. If you have unpaid dues, you need to know exactly how long TransUnion CIBIL retains your negative history and how lenders view those records over time.
The 7-Year Retention Rule
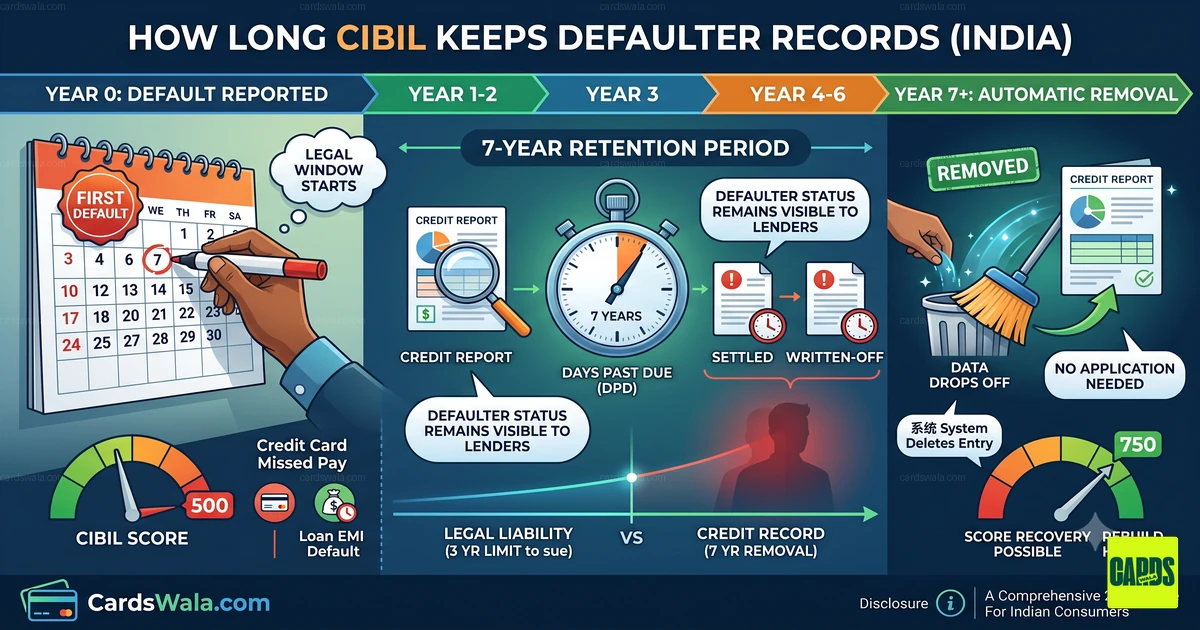
CIBIL does not erase your financial history quickly. As a general rule, your credit report retains records of defaults, late payments, and written-off accounts for approximately seven years from the date they are reported.
While a default stays visible on your report for up to seven years, its impact on your score gradually weakens. A fresh default destroys your credit immediately, but a five-year-old default carries far less weight—provided you have demonstrated flawless repayment behavior since then.
"Settled" vs "Closed" Status
If you cannot pay your full outstanding balance, a bank might offer a one-time settlement. You must understand the difference in how CIBIL records this.
| Account Status | What It Means | CIBIL Impact |
|---|---|---|
| Closed | You paid the entire principal, interest, and late fees. | Positive. Proves you clear your debts in full. |
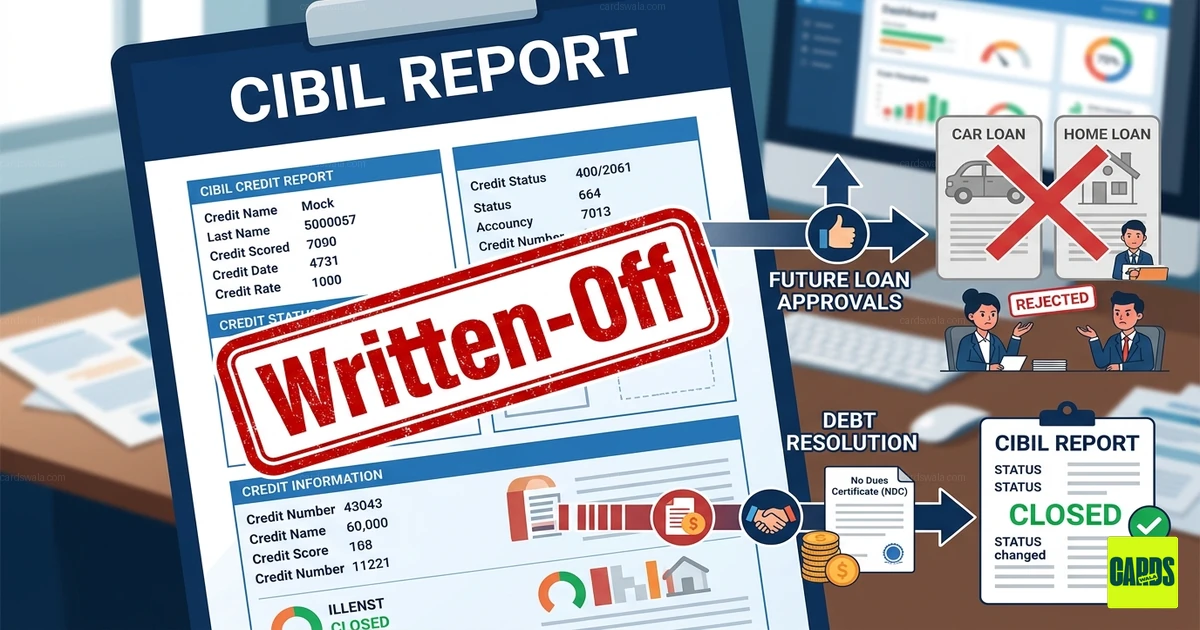
| Settled | You paid a compromised, lesser amount agreed upon with the bank. | Negative. Lenders view this as a partial default. |
A "Settled" tag remains on your report for about seven years and severely limits your chances of getting unsecured loans. For a deeper dive into this penalty, read our guide on debt settlement impact on CIBIL scores.
The NOC and Reporting Lag
When you finally clear your defaulted dues, the bank issues a No Objection Certificate (NOC). However, your CIBIL score will not jump the next day. It typically takes 1–3 billing cycles for the bank to report the updated status to the credit bureaus.
Once your report updates to "Closed," you must focus on rebuilding your profile. It usually takes around 12 months of disciplined financial behavior to see a meaningful score recovery. Follow our credit score rebuilding guide for actionable steps.
If you are just starting your recovery journey, explore our complete guide for Indian consumers on improving CIBIL scores. Once your score crosses the 750+ mark again, you can confidently compare premium options on our live card listings.
Check Out These Cards


CardsWala Crew
Credit Card Expert & Financial Writer